
100% Locally Owned, Independent and Free

100% Locally Owned, Independent and Free

Business 2 Business column: Christmas parties and tax law

Sponsored Content

Do you have a news tip? Click here to send to our news team.

Police appeal after alleged assault of security guards

Police have released an image of a man they believe may be able to assist with an investigation into the alleged assault of two More

Council defends tiered seawall amid heat, safety concerns

Sunshine Coast Council has backed the design and construction of a new terraced seawall at the region’s most popular beach amid worries it could More

Business domains surge as start-ups go online

Getting a business online is becoming less about juggling a collection of technical jobs and more about establishing a handful of digital essentials from More

Affordable housing plan gains support

A significantly revised housing development featuring 19 affordable rental dwellings has moved closer to approval after winning the support of most Noosa councillors. The proposal More

‘Drinks on us’: best mates celebrate monster win

Two Sunshine Coast mates have celebrated in style after winning $7.6 million. The men from Maroochydore were quick to shout everyone a drink at Club More

Two owners combine sites for rare sale

A unique double-site opportunity has emerged in one of the Sunshine Coast’s tightly held suburbs, with two adjoining properties hitting the market together. Lots 16 More

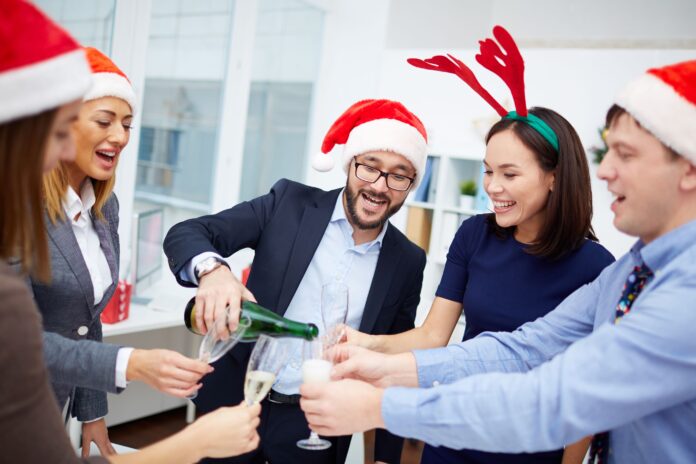
When providing food and drink, your business needs to consider Fringe Benefits Tax (FBT), Goods and Services Tax (GST) and Income Tax.

There are also different tax treatments if the entertainment you are providing is for employees, associates, clients or suppliers.

And it may differ depending on where you decide to hold your event.

Taxing Christmas parties at your workplace on a work day:

  • If you’re holding a Christmas party at your workplace and providing food and drink (including alcohol) on a work day, there may be no FBT payable for employees, clients, contractors or suppliers. These costs are FBT-exempt.
  • Unfortunately, that means that there will be no income tax deduction and no GST credits to be claimed for your Christmas party, either.
  • FBT exemptions may apply if the cost is less than $300. This amount is considered a ‘minor exempt benefit’.

Taxing Christmas parties held at a restaurant, bar or other venue:

  • If you’re holding your Christmas party at a location other than your workplace and providing food and drink (including alcohol) to employees and associates, FBT may be payable unless the costs of the party are less than $300 per employee.

Katrina Brennan, Principal, SRJ Walker Wayland Business Growth Advisors, Accountants and Auditors, Level 2/2 Innovation Parkway, Birtinya, 5301 9957, srjww.com.au

This column is part of our Business 2 Business (B2B) series featuring industry leaders sharing their expertise. For more great articles, SUBSCRIBE to our FREE news feed, direct to your inbox daily. All you need to do is enter your name and email below.
Subscribe to SCN’s free daily news email

This field is for validation purposes and should be left unchanged.
This field is hidden when viewing the form
[scn_go_back_button] Return Home
Share